4/16/25, 1:04 AM Gurleen Bajwa - AFF811/FIN801 011 - Financial Risk Management - W2025 - Toronto Metropolitan University
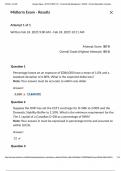
Midterm Exam - Results X
Attempt 1 of 1
Written Feb 24, 2025 9:00 AM - Feb 24, 2025 10:11 AM
Attempt Score 80 %
Overall Grade (Highest Attempt) 80 %
Question 1
Percentage losses on an exposure of $386,000 have a mean of 1.0% and a
standard deviation of 6.80%. What is the expected dollar loss?
Note: Your answer must be accurate to within one dollar.
Answer:
-3,860 % (3,860.00)
Question 2
Suppose the OSFI has set the CET1 surcharge for D-SIBs to 2.00% and the
Domestic Stability Buffer to 1.50%. What is the minimum requirement for the
Tier 1 capital of a Canadian D-SIB as a percentage of RWA?
Note: Your answer in must be expressed in percentage terms and accurate to
within 0.01%.
Answer:
12 v
Question 3
https://courses.torontomu.ca/d2l/ims/quizzing/user/quiz_submissions_attempt.d2|?isprv=&qi=445434&ai=10439053&isInPopup=0&cfql=0&fromQB=0... 1/14
, 4/16/25, 1:04 AM Gurleen Bajwa - AFF811/FIN801 011 - Financial Risk Management - W2025 - Toronto Metropolitan University
Consider a portfolio that is long 1,900 units of an index fund and short 7
forwards on that index with 10 months to expiry and a contract size of 100
index units. The stocks in the index have an average dividend yield of 0.6%
and the current 10-month interest rate is 3.4%. What is the delta of this
portfolio with respect to the index?
Note: Your answer must be accurate to within 0.1.
Answer:
1,203.5 v
Question 4
A bank uses the IMA approach to compute market risk and the IRB approach
to compute credit risk. It has computed RWA of $251 million for market risk,
$369 million for credit risk, and $100 million for operational risk. If it had used
the SA, its RWA would be $406 million for market risk and $561 million for
credit risk. Assuming it is now 2024, what would be the output floor for this
bank?
Note: Your answer must be expressed in $ millions and accurate to the
nearest $ million.
Answer:
587 v
Question 5
Consider a portfolio that is long 11 index options that have a delta of -0.05,
gamma of 0.040, vega of 0.030, and contract size of 100 index units and short
9 index options that have a delta of 0.25, gamma of 0.050, vega of 0.074, and
contract size of 100 index units. What is the gamma of this portfolio with
respect to the index?
Note: Your answer must be accurate to within 0.1.
Answer:
-10 v
https://courses.torontomu.ca/d2l/Ims/quizzing/user/quiz_submissions_attempt.d21?isprv=&Qqi=445434&ai=10439053&isInPopup=0&cfql=0&fromQB=0... 2/14
Midterm Exam - Results X
Attempt 1 of 1
Written Feb 24, 2025 9:00 AM - Feb 24, 2025 10:11 AM
Attempt Score 80 %
Overall Grade (Highest Attempt) 80 %
Question 1
Percentage losses on an exposure of $386,000 have a mean of 1.0% and a
standard deviation of 6.80%. What is the expected dollar loss?
Note: Your answer must be accurate to within one dollar.
Answer:
-3,860 % (3,860.00)
Question 2
Suppose the OSFI has set the CET1 surcharge for D-SIBs to 2.00% and the
Domestic Stability Buffer to 1.50%. What is the minimum requirement for the
Tier 1 capital of a Canadian D-SIB as a percentage of RWA?
Note: Your answer in must be expressed in percentage terms and accurate to
within 0.01%.
Answer:
12 v
Question 3
https://courses.torontomu.ca/d2l/ims/quizzing/user/quiz_submissions_attempt.d2|?isprv=&qi=445434&ai=10439053&isInPopup=0&cfql=0&fromQB=0... 1/14
, 4/16/25, 1:04 AM Gurleen Bajwa - AFF811/FIN801 011 - Financial Risk Management - W2025 - Toronto Metropolitan University
Consider a portfolio that is long 1,900 units of an index fund and short 7
forwards on that index with 10 months to expiry and a contract size of 100
index units. The stocks in the index have an average dividend yield of 0.6%
and the current 10-month interest rate is 3.4%. What is the delta of this
portfolio with respect to the index?
Note: Your answer must be accurate to within 0.1.
Answer:
1,203.5 v
Question 4
A bank uses the IMA approach to compute market risk and the IRB approach
to compute credit risk. It has computed RWA of $251 million for market risk,
$369 million for credit risk, and $100 million for operational risk. If it had used
the SA, its RWA would be $406 million for market risk and $561 million for
credit risk. Assuming it is now 2024, what would be the output floor for this
bank?
Note: Your answer must be expressed in $ millions and accurate to the
nearest $ million.
Answer:
587 v
Question 5
Consider a portfolio that is long 11 index options that have a delta of -0.05,
gamma of 0.040, vega of 0.030, and contract size of 100 index units and short
9 index options that have a delta of 0.25, gamma of 0.050, vega of 0.074, and
contract size of 100 index units. What is the gamma of this portfolio with
respect to the index?
Note: Your answer must be accurate to within 0.1.
Answer:
-10 v
https://courses.torontomu.ca/d2l/Ims/quizzing/user/quiz_submissions_attempt.d21?isprv=&Qqi=445434&ai=10439053&isInPopup=0&cfql=0&fromQB=0... 2/14