
Preview 4 out of 65 pages
Exam (elaborations)
RMIN 4000 UGA Test 1. Chapters 1-3 Questions with 100% Correct Answers | Latest Version 2024 | Expert Verified | Ace the Test
Preview 4 out of 65 pages
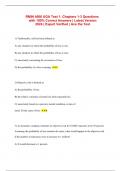
1) Traditionally, risk has been defined as A) any situation in which the probability of loss is one. B) any situation in which the probability of loss is zero. C) uncertainty concerning the occurrence of loss. D) the probability of a loss occurring. C 2) Objective risk is defined as A) the probability of loss. B) the relative variation of actual loss from expected loss. C) uncertainty based on a person's mental condition or state of mind. D) the cause of loss. B 3) An insurance company estimates its objective risk for 10,000 exposures to be 10 percent. Assuming the probability of loss remains the same, what would happen to the objective risk if the number of exposures were to increase to 1 million?
Document information
- Uploaded on
- April 18, 2024
- Number of pages
- 65
- Written in
- 2023/2024
- Type
- Exam (elaborations)
- Contains
- Questions & answers
$15.99
Wrong document? Swap it for free
Within 14 days of purchase and before downloading, you can choose a different document. You can simply spend the amount again.
Written by students who passed
Immediately available after payment
Read online or as PDF
Reputation scores are based on the amount of documents a seller has sold for a fee and the reviews they have received for those documents. There are three levels: Bronze, Silver and Gold. The better the reputation, the more your can rely on the quality of the sellers work.

