
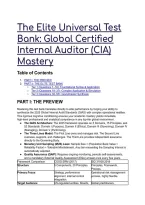
The Elite Universal Test
Bank: Global Certified
Internal Auditor (CIA)
Mastery
Table of Contents
1. PART I: THE PREVIEW
2. PART II: THE ELITE TEST BANK
○ Tier 1 (Questions 1–18): Foundational Syntax & Application
○ Tier 2 (Questions 19–37): Complex Application & Simulation
○ Tier 3 (Questions 38–55): Grandmaster Synthesis
PART I: THE PREVIEW
Mastering this test bank translates directly to elite performance by forging your ability to
synthesize the 2025 Global Internal Audit Standards (GIAS) with complex operational realities.
This rigorous cognitive conditioning ensures your academic mastery yields immediate,
high-level professional and analytical competence in any top-tier global environment.
● The GIAS Architecture: The 2025 framework operates on 5 Domains, 15 Principles, and
52 Standards. Domain I (Purpose), Domain II (Ethics), Domain III (Governing), Domain IV
(Managing), Domain V (Performing).
● The Three Lines Model: The First Line owns and manages risk. The Second Line
oversees, supports, and challenges. The Third Line provides independent assurance
directly to the Governing Body.
● Monetary Unit Sampling (MUS) Laws: Sample Size = (Population Book Value ×
Reliability Factor) ÷ Tolerable Misstatement. Any item exceeding the Sampling Interval is
automatically selected.
● Quality Assurance (QAIP): Requires ongoing monitoring, periodic self-assessments,
and a mandatory External Quality Assessment (EQA) at least once every five years.
Framework Comparison COSO ERM (2017) ISO 31000:2018
Structure 5 Components, 20 Principles. Principles, Framework,
Process.
Primary Focus Strategy, performance Operational risk management
alignment, internal control process, highly flexible.
integration.
Target Audience US-regulated entities, Boards, Global practitioners,
,Framework Comparison COSO ERM (2017) ISO 31000:2018
Executives. multi-sector organizations.
Certification Not certifiable; alignment only. Not certifiable; alignment only.
PART II: THE ELITE TEST BANK
Tier 1 (Questions 1–18): Foundational Syntax & Application
Q1: Under Domain I of the 2025 Global Internal Audit Standards, the core purpose of internal
auditing is defined. Which statement represents the PRIMARY mandate of the internal audit
function? A) To design and implement robust internal controls to mitigate operational risks. B) To
provide reasonable assurance over external financial reporting to regulatory bodies. C) To
strengthen the organization's ability to create, protect, and sustain value. D) To manage and
mitigate enterprise-wide risks on behalf of the board.
● Answer: C (To strengthen the organization's ability to create, protect, and sustain value.)
● Distractor Analysis:
○ A is incorrect: Designing controls is a management (First Line) responsibility; doing
so violates independence.
○ B is incorrect: This is the explicit primary objective of external statutory auditing, not
internal auditing.
○ D is incorrect: Managing risk is a First Line management function; internal audit
provides assurance over that process.
The Mentor's Analysis: The 2025 GIAS redefines the profession's mandate to focus on
organizational value. When facing functional boundary questions, the immediate priority is
separating management execution from independent assurance. By utilizing the Three Lines
Model, you bypass the common trap of assuming management responsibilities. Professional
Intuition: Internal audit assures value; management creates and manages the mechanisms of
value.
Q2: According to Standard 1.1 (Honesty and Professional Courage), an internal auditor
uncovers a minor but intentional expense fraud by a highly respected executive. The auditor is
pressured by the CFO to omit this from the final report. Which action is the ONLY acceptable
response? A) Omit the finding from the formal report but discuss it privately with the Audit
Committee. B) Document the finding in the workpapers but yield to the CFO's request for the
final report. C) Communicate the finding truthfully and take appropriate action despite potential
adverse consequences. D) Resign from the engagement immediately to avoid a conflict of
interest.
● Answer: C (Communicate the finding truthfully and take appropriate action despite
potential adverse consequences.)
● Distractor Analysis:
○ A is incorrect: Standard 1.1 demands transparency in all professional
communications, prohibiting the omission of material facts.
○ B is incorrect: Yielding to pressure compromises integrity and demonstrates a lack
of professional courage.
○ D is incorrect: Resignation is an extreme avoidance tactic, not an exercise of
professional courage or ethical duty.
The Mentor's Analysis: Standard 1.1 explicitly demands professional courage. When facing
management pressure to suppress findings, the immediate priority is objective, factual reporting.
By utilizing Professional Courage, you bypass the common trap of subordinating judgment to
, executive influence. Professional Intuition: Integrity demands you tell the truth, especially
when doing so carries personal or professional risk.
Q3: A Chief Audit Executive (CAE) was previously the Director of IT Procurement before
transferring to Internal Audit six months ago. The CAE is scheduling the annual audit plan.
Regarding IT Procurement, what is the MOST APPROPRIATE safeguard under Standard 2.2
(Safeguarding Objectivity)? A) The CAE may oversee the audit but must not perform the testing
directly. B) The CAE must assign the audit to an external third party or have an independent
party oversee it. C) The CAE may perform the audit since they possess expert knowledge of the
procurement system. D) The CAE must delay the audit for an additional six months until a full
year has passed.
● Answer: B (The CAE must assign the audit to an external third party or have an
independent party oversee it.)
● Distractor Analysis:
○ A is incorrect: Overseeing an audit of a function one was responsible for within the
last 12 months constitutes a self-review impairment.
○ C is incorrect: Expert knowledge does not negate the impairment of objectivity
caused by prior responsibility.
○ D is incorrect: Delaying the audit ignores the organization's immediate risk
assessment needs; independent oversight allows the audit to proceed securely.
The Mentor's Analysis: Objectivity is impaired when auditors review their own previous work.
When facing a self-review threat, the immediate priority is removing the conflicted individual
from oversight. By utilizing Independent Oversight, you bypass the common trap of
compromising the engagement's credibility. Professional Intuition: You cannot grade your own
homework; a strict 12-month cooling-off period applies to all previous operational roles.
Q4: A multinational corporation has adopted the IIA's Three Lines Model. Which function is
STRICTLY categorized as a Second Line role? A) The Chief Financial Officer executing daily
cash management. B) The IT Security Director designing network firewalls. C) The Chief
Compliance Officer monitoring adherence to regulatory requirements. D) The Chief Audit
Executive evaluating the enterprise risk management framework.
● Answer: C (The Chief Compliance Officer monitoring adherence to regulatory
requirements.)
● Distractor Analysis:
○ A is incorrect: Executing daily operations and managing risk is a First Line role.
○ B is incorrect: Designing and implementing controls is a First Line risk ownership
role. * D is incorrect: The CAE operates in the Third Line, providing independent
and objective assurance.
The Mentor's Analysis: The Three Lines Model separates risk ownership, risk monitoring, and
risk assurance. When facing role classification questions, the immediate priority is identifying
who owns the risk versus who monitors it. By utilizing the Second Line definition (expertise,
support, monitoring, and challenge), you bypass the common trap of confusing risk execution
with risk oversight. Professional Intuition: First line executes and owns; Second line monitors
and advises; Third line assures independently.
Q5: When utilizing Monetary Unit Sampling (MUS) for accounts receivable, which population
characteristic makes MUS the OPTIMAL choice? A) The population contains a massive volume
of zero and negative balances. B) The auditor expects a high frequency of large
understatements. C) The auditor expects few misstatements and wants to automatically bias
selection toward larger dollar balances. D) The auditor needs to test the operating effectiveness
of authorization controls.


