
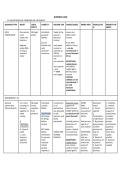
BUSINESS LAW
CH 16 METHODS OF CARRYING ON A BUSINESS
BUSINESS TYPE WHAT LEGAL LIABILITY INCOME TAX GAINS/LOSSES MORE INFO DISSOLUTIO PRIORITY OF
ENTITY N DEBTS
SOLE One person NO legal Unlimited Taxed at the Losses can
PROPRIESHIP runs/ entity personal person’s offset other
makes the liability personal income
business income
Can be If can NOT
Register limited only use/report offset in the yr
under BNA with income in – can be
if using a contract/ calendar yr carried back 3
business insurance OR file yr and forward
name election to 20 yrs
use
non-calenda EXCEPTION:
r capital losses
non-calenda only offset
r year capital gains
** MNR NOT business
must agree income
CAPITAL
LOSSES can be
carried back 3
yrs and
forward
indefinitely
PARTNERSHIP (3)
General 2 or more NO legal Unlimited income/loss Business losses MORE Dissolved 1. Creditors
partnership carrying on entity, ( jointly es of against all INFO: when: 2. Limited
Partnership PA business separate liable) partnership other income Actions of 1. Terms partners in
together to from are allocated CARRY OVER: 3 one partner expired respect of
make partners EXCEPTION: to the yrs back and 20 bind the 2. share/comp
money NOT liable partners and years forward others Termination ensation
for things taxed of adventure 3.limited
3 before personally Limited partner Partners are 3. By partner partner
CRITERIAS: partner deduction of agents of giving notice contribution
a. Business business one another to other 4.general
B. .View of BUT liable losses– limited partners of partner (
profit before LOSSES ARE to investment EXCEPTION: date of other than
c. carry retirement. SHARED of partnership partners notice capital
business For person EQUALLY that are 4. Death of profits)
together to be EXCEPTION: NOT acting insolvency of 5. General
for profit released: capital losses within the a partner partner (
retired can only be scope of 5. Event of capital)
partner used to reduce normal unlawful
requires a capital gains ( business business
, three-way NOT business activities application
agreement ( losses) by partner to
novation) CARRY OVER: 3 Ordinary court
yrs back and business ** can be
forward decisions avoided by
indefinitely are made written
the majority contract
FILING TAX: of partners agreement
File information
return for each General
fiscal period partner
with CRA and dies/retires/
give copy to becomes
each partner incapable of
managing
property
court
mandates
dissolution
*Can be
avoided in
contract
agreement
Declaration
of dissolution
filed with
registrar of
partnerships
Limited 1 or more NO legal General Share profits
partnership general entity partner / based on
(LPA) (CAN NOT partners ( separate GENERAL contribution
contribute unlimited from LIABILITY unless:
services) liability) + 1 partners – unlimited a. otherwise
● File or more liability in
declaration limited agreement
with partner ( Limited OR
ministry of limited partner/ b. not
public + liability) limited enough to
business liability pay debts
service Limited – limited to
delivery via partner amount Filing reqs
ONtario CAN NOT contributed for ALL
business manage or OR agreed File info
registry control to return for
● Expires business – contribute each fiscal
every 5 becomes in the period of
years and general business partnership
requires a partner with CRA
renewal Limited
IF CHANGES TO Can be partner is a


