
d101 cost and managerial accounting UPDATED ACTUAL
Questions and CORRECT Answers
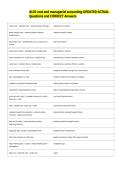
actual price - standard price x actual quantity purchased materials price variance
actual quantity used - standard quantity allowed x materials quantity variance
standard price
actual labor rate - standard labor rate x actual hours labor rate variance
worked
actual hours worked - standard hours x standard rate labor efficiency variance
actual overhead cost - actual hours x standard rate manufacturing overhead spending variance
actual hours - standard hours x standard rate manufacturing overhead efficiency variance
total contribution/total sales weighted contribution margin (cm) ratio formula
fixed cost/weighted cm ratio breakeven sales formula (sales mix problem)
weighted cm ratio then breakeven sales order of doing a sales mix problem
contribution margin/operating income degree of operating leverage (DoL) formula
(price per unit x units) - (variable cost per unit x units) - cvp formula (broken down)
fixed cost = profit
sales - variable cost - fixed cost = profit cvp formula (not broken down)
materials needed for production + desired ending standard direct materials budget formula
inventory - beginning inventory
sales for the month + desired ending inventory - standard production budget formula
beginning inventory
budgeted mfg overhead cost/budgeted base predetermined overhead rate
debit mfg overhead or credit cogs applied overhead is higher than actual overhead
begin finished goods + cogsm - ending finished goods + unadjusted cogs
underapplied
begin wip + total mfg costs - ending wip cogsm


