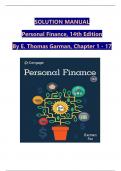
SOLUTION MANUAL
Personal Finance, 14th Edition
By E. Thomas Garman, Chapter 1 - 17
TABLE OF CONTENTS
Part I: FINANCIAL PLANNING.
1. Understanding Personal Finance.
2. Career Planning.
3. Financial Statements, Goals, and Budgets.
Part II: MONEY MANAGEMENT.
4. Managing Income Taxes.
5. Managing Checking and Savings Accounts.
6. Building and Maintaining Good Credit.
7. Credit Cards and Consumer Loans.
8. Vehicles and Other Major Purchases.
9. Obtaining Affordable Housing.
Part III: INCOME AND ASSET PROTECTION.
10. Managing Property and Liability Risk.
11. Planning for Health Care Expenses.
12. Life Insurance Planning.
Part IV: INVESTMENTS.
13. Investment Fundamentals.
14. Investing in Stocks and Bonds.
15. Mutual and Exchange-Traded Funds.
16. Real Estate and High-Risk Investments.
17. Retirement and Estate Planning.
Solution and Answer Guide
GARMAN/FOX, PERSONAL FINANCE 14E, CHAPTER 1: THINKING LIKE A FINANCIAL PLANNER
TABLE OF CONTENTS
Answers to Chapter Concept Checks ................................................................................................ 2
What Do You Recommend Now?...................................................................................................... 4
Let’s Talk About It......................................................................................................................................................... 5
Do the Math ......................................................................................................................................... 6
Financial Planning Cases .................................................................................................................... 8
Extended Learning ............................................................................................................................ 10
ANSWERS TO CHAPTER CONCEPT CHECKS
LO1.1 Recognize the keys to achieving financial success.
1. Explain the five steps in the financial planning process.
Answer: There are five fundamental steps to the personal financial planning process: (1) evaluate
your financial health to your education and career choice; (2) define your financial goals; (3)
develop a plan of action to achieve your goals; (4) implement spending and saving plans to
monitor and control progress toward your goals; and (5) review your financial progress and make
changes as appropriate.
2. Distinguish among financial success, financial security, and financial happiness.
Answer: Financial success is the achievement of financial aspirations that are desired, planned,
or attempted. Success is defined by the individual or family that seeks it. Financial success may be
defined as being able to live according to one’s standard of living. Financial security is that
comfortable feeling that your financial resources will be adequate to fulfill any needs you have as
well as your wants. Financial happiness is the experience you have when you are satisfied with
money matters. People who are happy about their finances will see a spillover into positive
feelings about life in general.
3. Summarize what you will accomplish studying personal finance.
Answer: Several things can be accomplished by studying personal finance. Recognize how to
manage unexpected and expected financial events. Pay as little as possible in income taxes.
Understand how to effectively comparison shop for vehicles and homes. Protect what we own.
Invest wisely. Accumulate and protect the wealth that we may choose to spend during our non
working years (e.g., retirement) or donate.
4. What are the building blocks to achieving financial success?
Answer: The building blocks for achieving financial success include a foundation of regular
income that provides the means to support your lifestyle and save for desired goals in the future.
The foundation supports a base of various banking accounts, insurance protection, and employee
benefits. Then we can establish goals, a recordkeeping system, a budget, and an emergency
savings fund. We will also manage various expenses such as housing, transportation, insurance,
and the payment of taxes. We will also need to handle credit, savings, and educational costs.
Finally, we invest in various investment alternatives such as mutual funds, stocks, and bonds,
often for retirement. As a result of all these building blocks, we are more apt to have a financially
successful life.
LO1.2 Understand how the economy affects your personal financial success.
1. Summarize the phases of the business cycle.
Answer: The business cycle entails a wavelike pattern of rising and falling economic activity as
measured by economic indicators like unemployment rates or the gross domestic product. The
phases of the business cycle include expansion (preferred stage—production is high,
unemployment low, interest rates low or falling, stock market and consumer demand high), peak,
contraction, downturn, trough, and recovery.
2. Describe two statistics that help predict the future direction of the economy.
Answer: Forecasting the state of the economy involves predicting, estimating, or calculating what
will happen in advance. We need to be able to forecast the state of the economy, inflation, and
interest rates so that we have advance warning of the directions and strength of changes in
economic trends since they will affect our personal finances. Two statistics we could watch are the
consumer confidence index (how consumers feel about the economy and their personal finances)
and the index of leading economic indicators (composite index, averages ten components of
economic growth).
3. Give an example of how inflation affects income and consumption.
Answer: Inflation reduces the purchasing power of the dollar. This means that our income will
not go as far and, thus, in real terms will be lowered by inflation. Because items cost more, we will
have to consume less and may cut back on some expenditures to be able to afford those with a
higher priority.
LO1.3 Think like an economist when making financial decisions.
1. Define opportunity cost and give an example of how opportunity costs might affect
your financial decision making.
Answer: The opportunity cost of a decision is measured as the value of the next-best alternative
that must be forgone. If we, for example, put our retirement savings in a regular savings account
instead of in a tax- sheltered retirement account, we may be forgoing the tax benefits associated
with investing in retirement accounts such as IRAs or 401(k) plans. In another example, if we
decide to borrow the maximum student loan amount for which we qualify to live a bit more
comfortably while in college, we will not be able to live as nicely, save as much for the down
payment on a home or save for retirement once we graduate because of the higher loan
payments.
2. Explain and give an example of how marginal utility and marginal cost make some
financial decisions easier.
Answer: Marginal analysis focuses on the next increment of usefulness or cost when making
financial decisions. Marginal utility is the extra satisfaction derived from having one more
incremental unit of a product or service. Marginal cost is the additional cost of that unit. When
marginal utility exceeds marginal cost, and we compare the two, we can make better financial
decisions. As an example, if you must fly to some destination, is the marginal cost of checking a
bag using a carry-on worth the marginal utility?
3. Describe and give an example of how your marginal income tax rate can affect financial
decision making.
Answer: As our income rises, we will find ourselves in higher and higher tax brackets. One type of
decision that is affected by income taxes is how we should invest for retirement. We might want
to invest through a 401(k) plan instead of keeping our retirement money in a savings account,
which is taxable.
Since most types of income are taxable, it is important that we understand the impact of income
taxes on financial decisions. Of particular importance is the marginal tax rate (the tax rate at which
our last dollar earned is taxed). If we are in the 25 percent marginal tax bracket, we will get to
keep 75 percent (100 percent minus 25 percent) of our last taxable dollar earned. If the income is
tax-free income, on the other hand, we would get to keep 100 percent of it. Therefore, it is
important to know our marginal tax rate as well as what types of income are subject to federal
income taxes. It is also important to remember the impact of state income taxes and Social
Security taxes.
LO1.4 Perform time value of money calculations in personal financial decision making.
1. What are the two common questions about money?
Answer: The two common questions about money are its future value and present value. Future
value is what investment or series of investments will be at a point in the future. Present value is
how much we would need to invest today and/or in a series of future investments to provide
some amount in the future.
2. Explain the difference between simple interest and compound interest, and describe
why that difference is critical.
Answer: Simple interest is money paid on a principal amount for a given number of years. The
interest is paid only on the principal (the original amount invested). For example, we might put
$1,000 in a bank savings account at 5 percent interest for one year. We would have accumulated
$50 in that year.
Compound interest is interest paid on interest and principal. For example, if we leave your
$1,000 on deposit and do not withdraw the $50 interest at the end of the year, we will earn
interest on both the deposit and the interest earned during the first year. This difference in the
types of interest paid is important as compound interest is the basic principle of accumulating
wealth. If we invest regularly over time, our money will grow due to the power of compound
interest.
3. Use Table 1-1 to calculate the future value of (a) $2,000 at 5 percent for four years, (b)
$4,500 at 9 percent for eight years, and (c) $10,000 at 6 percent for ten years.
Answer:
a.
$2,000 at 5 percent for four years would equal $2,431 ($2,000 × 1.2155).
b. $4,500 at 9 percent for eight years would equal $8,966.70 ($4,500 × 1.9926).
c.
$10,000 at 6 percent for 10 years would equal $17,908 ($10,000 × 1.7908).
[return to top]
WHAT DO YOU RECOMMEND NOW?
Now that you have read the chapter on the importance of personal finance, what do you recommend to
Jing Wáng in the case at the beginning of the chapter.
1. Participating in her employer’s 401(k) retirement plan?
Answer: Jing should participate in her employer’s plan because her contributions reduce her
taxable income and will grow tax-sheltered until withdrawn at retirement. By doing so, she will
qualify for her employer contributions, thereby receiving additional tax-sheltered income that will
go directly into her retirement account. If Jing contributed 8 percent of her salary, her employer
would match it with 4 percent for a total of 12 percent. Her total contribution would be $9,600
based on her salary of $80,000.
2. Understanding the effects of her marginal tax rate on her financial decisions?
Answer: Jing should use her marginal tax rate to assess how changes in her income and the
financial decisions she will make would be affected by taxes. For every extra dollar that she
contributes to her retirement plan, for example, she will save $0.25 in taxes if she is in the 25
percent tax bracket. Also, if she earns an extra dollar, it will be taxed at her marginal rate.
3. Considering the current state of the economy in her personal financial planning?
Answer: Jing should stay informed about economic trends as indicated in changes in the gross
domestic product, index of leading economic indicators, and consumer price index. She should also
keep track of the federal funds rate as an indicator of interest rates in the economy. She should be
able to make her own estimate for economic growth, inflation, and interest rates over the next
couple of years.
4. Using time value of money considerations to project what her Roth-IRA might be worth at
age 63?
Answer: Jing could use Appendix A.1 to calculate how much her IRA fund (currently $2,000)
would grow in 40 years. She would need to assume a rate of return on the funds. An 8 to 10
percent rate would be appropriate given the investment opportunities available to her in her IRA.
At 8 percent, her account would be worth about $43,449 (21.7245 × $2,000).
5. Using time value of money considerations to project what her 401(k) plan might be worth
at age 63 if she were to participate fully?
Answer: Jing could use Appendix A.3 to calculate how much her contributions would grow in
40 years. She would need to assume a rate of return on the funds. An 8 percent rate would be
appropriate given the investment opportunities available to her in her 401(k). At 8 percent, her
account would be worth about
$2,486,942 (259.0565 × $9,600; $6,400 of Jing’s money and $3,200 from her employer).
6. Saving for retirement versus paying off student loans?
Answer: At a minimum Jing should contribute 8 percent of her salary to her retirement savings
to take advantage of her employer’s match. Jing’s retirement savings capitalizes on compounding
and the time value of money. Employer matching for retirement is free money and should not be
left on the table. Jing is paying off $35,000 in student loans and paying off any loan does provide
a guaranteed rate of return.
However, it is unlikely that the return from paying off the student loan will exceed the value of the
retirement savings when it is combined with the employer match.
[return to top]
LET’S TALK ABOUT IT
1. Economic Growth. How do federal government efforts help stimulate economic growth? How
do these efforts affect consumers?
Answer: Answers will vary depending on the student’s own financial situation. Tax cuts may help
students in the lower tax brackets. Efforts to revive the economy will help students keep or obtain
jobs. Education- related credits will help college students. Efforts to help people buy their first
home will help students who might be so interested.
2. The Business Cycle. Where do you think the United States is in the economic cycle now, and
where does it seem to be heading? List some indicators that suggest in which direction it may
move.
Answer: At the time this edition was published, the economy was expanding with annual growth of
around
2.3 percent. The gross domestic product was edging up, but growth has been an uneven pattern.
Consumer spending is up, despite inflation being at a four-decade high. Interest rates were raised
by the Fed, so borrowing is more expensive. The unemployment rate is declining slightly and is
forecast to continue to decline. Many people are benefiting from rising wages due to tighter labor
markets. Along with inflation, supply chain disruptions have been an issue. There has been an
exuberant real estate market throughout the pandemic but that is starting to cool due to the rise in
interest rates and inflation. Federal infrastructure spending programs were about to kick in and help
some of the economic indicators.
3. Personal Finance Mistakes. What are some common mistakes that people make in personal
finance? Name two that might be the worst, and why?
Answer: Eleven mistakes that people make in personal finance are failing to (1) engage in long
term personal financial planning, (2) engage in long-term budgeting, (3) engage in short-term
budgeting, (4) establish a cash reserve in case of emergencies, (5) save at a rate that is sufficiently
high, (6) establish adequate insurance protection, (7) manage income tax liabilities
advantageously, (8) limit credit card debt,
(9) manage expenditures so as to prevent unexpected expenditures on a credit card, (10) engage
in investment planning, and (11) engage in retirement and estate planning. All eleven mistakes
are important. The three most important mistakes are saving at a rate that is too low, and
inadequate retirement and estate planning. Americans save at a rate that is very low. If you save
just 1 percent more of your pay, you will reap a high return at retirement. Also, if you withdraw
money from your tax-sheltered retirement plan before retirement, you will have a substantial
shortfall when it comes time to re
Content preview
SOLUTION MANUAL
Personal Finance, 14th Edition
By E. Thomas Garman, Chapter 1 - 17
,TABLE OF CONTENTS
Part I: FINANCIAL PLANNING.
1. Understanding Personal Finance.
2. Career Planning.
3. Financial Statements, Goals, and Budgets.
Part II: MONEY MANAGEMENT.
4. Managing Income Taxes.
5. Managing Checking and Savings Accounts.
6. Building and Maintaining Good Credit.
7. Credit Cards and Consumer Loans.
8. Vehicles and Other Major Purchases.
9. Obtaining Affordable Housing.
Part III: INCOME AND ASSET PROTECTION.
10. Managing Property and Liability Risk.
11. Planning for Health Care Expenses.
12. Life Insurance Planning.
Part IV: INVESTMENTS.
13. Investment Fundamentals.
,14. Investing in Stocks and Bonds.
15. Mutual and Exchange-Traded Funds.
16. Real Estate and High-Risk Investments.
17. Retirement and Estate Planning.
Solution and Answer Guide
GARMAN/FOX, PERSONAL FINANCE 14E, CHAPTER 1: THINKING LIKE A FINANCIAL PLANNER
TABLE OF CONTENTS
Answers to Chapter Concept Checks................................................................................................ 2
What Do You Recommend Now?...................................................................................................... 4
Let’s Talk About It......................................................................................................................................................... 5
Do the Math ......................................................................................................................................... 6
Financial Planning Cases .................................................................................................................... 8
Extended Learning ............................................................................................................................10
, ANSWERS TO CHAPTER CONCEPT CHECKS
LO1.1 Recognize the keys to achieving financial success.
1. Explain the five steps in the financial planning process.
Answer: There are five fundamental steps to the personal financial planning process: (1) evaluate
your financial health to your education and career choice; (2) define your financial goals; (3)
develop a plan of action to achieve your goals; (4) implement spending and saving plans to
monitor and control progress toward your goals; and (5) review your financial progress and make
changes as appropriate.
2. Distinguish among financial success, financial security, and financial happiness.
Answer: Financial success is the achievement of financial aspirations that are desired, planned,
or attempted. Success is defined by the individual or family that seeks it. Financial success may be
defined as being able to live according to one’s standard of living. Financial security is that
comfortable feeling that your financial resources will be adequate to fulfill any needs you have as
well as your wants. Financial happiness is the experience you have when you are satisfied with
money matters. People who are happy about their finances will see a spillover into positive
feelings about life in general.
3. Summarize what you will accomplish studying personal finance.
Answer: Several things can be accomplished by studying personal finance. Recognize how to
manage unexpected and expected financial events. Pay as little as possible in income taxes.
Understand how to effectively comparison shop for vehicles and homes. Protect what we own.
Invest wisely. Accumulate and protect the wealth that we may choose to spend during our non-
working years (e.g., retirement) or donate.
4. What are the building blocks to achieving financial success?
Answer: The building blocks for achieving financial success include a foundation of regular
income that provides the means to support your lifestyle and save for desired goals in the future.
The foundation supports a base of various banking accounts, insurance protection, and employee
benefits. Then we can establish goals, a recordkeeping system, a budget, and an emergency
savings fund. We will also manage various expenses such as housing, transportation, insurance,
and the payment of taxes. We will also need to handle credit, savings, and educational costs.
Finally, we invest in various investment alternatives such as mutual funds, stocks, and bonds,
often for retirement. As a result of all these building blocks, we are more apt to have a financially
successful life.
LO1.2 Understand how the economy affects your personal financial success.
1. Summarize the phases of the business cycle.
Answer: The business cycle entails a wavelike pattern of rising and falling economic activity as
measured by economic indicators like unemployment rates or the gross domestic product. The