
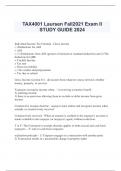
TAX4001 Laursen Fall2021 Exam II STUDY GUIDE 2024
Individual Income Tax Formula - Gross income (-) Deductions for AGI = AGI (-) 1) Deductions from AGI (greater of itemized or standard deduction) and 2) The deduction for QBI = Taxable Income x Tax rate = Gross tax liability (-) Tax credits and prepayments = Tax due or refund Gross Income (section 61) - all income from whatever source derived, whether money, property, or services Taxpayers recongize income when: - 1) receiving economic benefit 2) realizing income 3) there is no provision allowing them to exclude or defer income from gross income Constructive receipts doctrine - taxpayer must realize and recognize income when actually or constructively received Constructively received - When an amount is credited to the taxpayer's account or made available to the taxpayer (or taxpayer's agent) without restriction. T or F: The Constructive receipts doctrine applies to both accrual and cash basis taxpayers. - F: only to cash basis taxpayers realization principle - 1) Taxpayer engages in a transaction with another party 2) Transaction results in a measurable change in property rights form of receipt - taxpayers realize income whether they receive money, property, or services in a transaction tax benefit rule - Refunds on an expense deducted in a previous year are included in gross income to the extent it reduced taxes in the year of deduction T or F: A taxpayer who took the standard deduction in the prior year and received a refund in the current year never adds the refund to the current gross income. - T: no tax benefit was received The taxpayer receives a refund in the current year of $3,000 and used itemized deductions of $15,000 in the prior year. The standard deduction was $6,300 in the prior year. What counts as income in the current year? What if the itemized deductions were $8,300 in the prior year? - The full $3,000 counts as income in the current year since $15,000 -6,300 = $8,700 additional deduction (tax benefit) $2,000 would count as income $8,300 - 6,300 = $2,000 In 2020 Courtney paid $3,500 in Ohio state income taxes, and she included this payment with her other itemized deductions when she filed her federal income tax return in March of 2021. Courtney filed her 2020 federal return as a head of household and claimed $20,750 of itemized deductions (including $3,500 state income taxes, $2,500 of real estate taxes, $8,000 of mortgage interest expense, and $6,750 of charitable contributions). She also filed an Ohio state income tax return in March of 2021 and discovered she only owed $3,080 in Ohio income tax for 2020. Hence, Courtney received a $420 refund of her Ohio income tax in June of 2021. Applying the tax benefit rule, how much of the $420 refund, if any, is Courtney required to include in her gross income for 2021 given that the standard deduction for head of household filing status in 2020 was $18,650? - The full $420 $20,750- $18,650 = $2,100 and $3,500 + $2,500 10,000 so we do not need to consider the limit on tax deductions Claim of right doctrine (judicial court doctrine) - Income received with no restrictions is income now ex: end of year bonus would be counted as realized income
Document information
- Uploaded on
- June 20, 2024
- Number of pages
- 16
- Written in
- 2023/2024
- Type
- Exam (elaborations)
- Contains
- Questions & answers


