
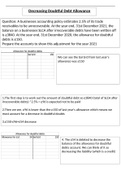
Decreasing Doubtful Debt Allowance
Question: A businesses accounting policy estimates 2.5% of its trade
receivables to be unrecoverable. At the year end, 31st December 2021, the
balance on a businesses SLCA after irrecoverable debts have been written off
is £3840. At the year end, 31st December 2020, the allowance for doubtful
debts is £150.
Prepare the accounts to show this adjustment for the year 2021
We can see the bal b/d from last year’s
allowance was £150
1.The first step is to work out the amount of doubtful debt so £3840 (total of SLCA after
irrecoverable debts) *2.5% = £96 is expected not to be paid
2.Then we see, £96 is lower than the £150 of last year’s allowance which means we
must account for a decrease in doubtful doubts
3.£150-£96=£54 decrease
4. The £54 is debited to decrease the
balance of the allowance for doubtful
debts account. We can think of it as
decreasing the liability (which is a credit)


