
CHAPTER 6: GENERAL DEDUCTIONS
CHAPTER OVERVIEW
• Subsequent to determining ‘income’ [gross income - exempt income] the
next step in calculation of taxable income = deduct all
amounts allowed as tax deductions under S11(a)
• Expenditure & losses are deductible if ALL requirements in the
general deduction formula are met, unless specifically
provided for elsewhere in ITA
• S11(a) contains positive terms [what may be deducted] & S23 contains
negative terms [prohibitions on certain deductions]
- Prohibitions in S23 must be considered in conjunction with
S11(a) general deduction formula
• Note: fact that IFRS or business practice would treat an amount as deductible is irrelevant
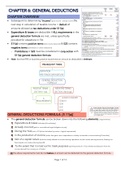
PRE-REQUISIT: TRADE
DEFINITION
PRE-TRADE EXPENDITURE
GENERAL DEDUCTION
FORMULA
POSITIVE TERMS NEGATIVE TERMS
[SECTION 11(a)] [SECTION 23(b) & (g)]
6 ALWAYS CONSIDER
REQUIREMENTS S23(a)-(r)
S23B
S23C
S23H
GENERAL DEDUCTIONS FORMULA: [S 11(a)]
• The general deduction formula can be broken down into the following elements: [requirements]
1) Expenditure & losses [voluntary & involuntary]
2) Actually incurred [paid or unconditional legal obligation to pay]
3) During the YoA [not in S11(a) but laid down by courts = logical requirement]
4) In the production of income [action that gave rise to expenditure is closely connected to income-earning B activities]
5) Not of a capital nature [must be closely related to income-earning operations not the income-earning structure, floating not
fixed capital, not create enduring benefit]
6) To the extent that it is laid out for trade purposes [opening words of s 11(a): allowed as deduction from the
income derived from carrying on of trade]
All the above requirements must be met before an amount can be deducted ito the general deduction formula
Page 1 of 13
, 1) Expenditure & Losses:
• Following terms have been defined through case law:
Expenditure Losses
- Voluntary payment of money/movement of assets - Involuntary deprivation
- Action of spending funds/disbursement/ - Within context of S11(a) means
consumption & ∴ the amount of money spent losses of floating capital employed
- Diminution [even if temporary] or, at very least, a in the trade which produces income
movement of assets of the person who expends
2) Actually Incurred: [actually incurred ≠ actually paid ≠ necessarily incurred]
• Actually incurred doesn’t mean necessarily incurred
• Only expenditure which taxpayer has incurred an unconditional legal obligation/liability can
be deducted
• If liability is contingent upon some condition = it’s NOT ‘actually incurred’
- It only becomes ‘actually incurred’ once the condition has been met
- ∴ if no definite & absolute liability to pay amount = expenditure NOT ‘actually incurred’
• Expenditure is ‘actually incurred’ in tax year in which the liability to pay it arises & NOT in tax
year in which it’s actually paid
• Estimates of contingent [uncertain] liabilities = NOT expenditure actually incurred
• If unconditional legal liability was incurred but can’t be quantified = S24M says unquantified
portion of expenditure only deemed to be incurred in YoA when can be quantified
• Deduction in respect of a disputed claim can’t be claimed if outcome of dispute is
undetermined at end of the YoA
3) During the Year of Assessment: [logical requirement]
• Expenditure is only deductible during the YoA in which it was ‘actually incurred’
- ∴ it can’t be carried forward to claim in a subsequent year or carried backward to claim in a
previous year
Exceptions: S 24M & S 23H
• To be deductible it’s not necessary that expenditure produce income in year that it was
incurred & ∴ it’s deductible even if income will only be earned in future years
4) In the Production of Income: [hardest requirement to understand]
‘Income’ = Gross Income – Exempt Income
• To determine whether expenditure was ‘in the production of income’ = 2 aspects must be
determined:
(1) The action that gave rise to the expenditure & the purpose of that action
(2) If the action [expenditure] is so closely connected with [or a necessary concomitant of] the income-
earning business activities of taxpayer
Page 2 of 13


