GCT calculation:
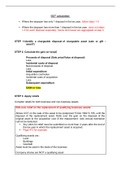
Where the taxpayer has only 1 disposal in the tax year, follow steps 1-5
Where the taxpayer has more than 1 disposal in the tax year, carry out steps
1-3 for each disposal separately. Gains and losses are aggregated at step 4.
STEP 1:Identify a chargeable disposal of chargeable asset (sale or gift –
asset?)
STEP 2: Calculate the gain (or loss)£
Proceeds of disposal (Sale price/Value at disposal)
Less
Incidental costs of disposal
Net proceeds of disposal
Less
Initial expenditure
Acquisition cost/value
Incidental costs of acquisition
Less
Subsequent expenditure
GAIN or loss
STEP 3: Apply reliefs
Consider reliefs for both business and non-business assets
Roll-over relief on the replacement of qualifying business assets:
Allows CGT on the sale of the asset to be postponed TCGA 1992 S 155- until the
disposal of the replacement asset. Rolls over the gain on the disposal of the
original asset to the acquisition cost of the replacement- note annual exemption
cannot be deducted.
Any claim for relief must be submitted no more than 4 years after the end of
the tax year in which the replacement asset is acquired.
Page 413 for example
Qualifying assets are :
- Land
- Buildings
- Goodwill
Asset must be used in the trade of the business
Company shares are NOT a qualifying asset
Where the taxpayer has only 1 disposal in the tax year, follow steps 1-5
Where the taxpayer has more than 1 disposal in the tax year, carry out steps
1-3 for each disposal separately. Gains and losses are aggregated at step 4.
STEP 1:Identify a chargeable disposal of chargeable asset (sale or gift –
asset?)
STEP 2: Calculate the gain (or loss)£
Proceeds of disposal (Sale price/Value at disposal)
Less
Incidental costs of disposal
Net proceeds of disposal
Less
Initial expenditure
Acquisition cost/value
Incidental costs of acquisition
Less
Subsequent expenditure
GAIN or loss
STEP 3: Apply reliefs
Consider reliefs for both business and non-business assets
Roll-over relief on the replacement of qualifying business assets:
Allows CGT on the sale of the asset to be postponed TCGA 1992 S 155- until the
disposal of the replacement asset. Rolls over the gain on the disposal of the
original asset to the acquisition cost of the replacement- note annual exemption
cannot be deducted.
Any claim for relief must be submitted no more than 4 years after the end of
the tax year in which the replacement asset is acquired.
Page 413 for example
Qualifying assets are :
- Land
- Buildings
- Goodwill
Asset must be used in the trade of the business
Company shares are NOT a qualifying asset