*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
4:03:13 AM1
4:03:13
of 3Page
AM1
4:03:13
of1WGU
3Page
AM1 of
C239
1WGU
3Page
Final
C239
1WGU
Exam
Final
C239
KeyExam
Study
Final
KeyExam
Guide.pdf2026/10/23Page
Study
KeyGuide.pdf2026/10/23Page
Study Guide.pdf2026/10/23Page
1 of 3 1 of 3 1 of 3
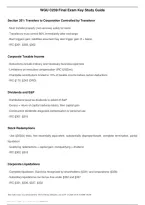
WGU C239 Final Exam Key Study Guide
Section 351: Transfers to Corporation Controlled by Transferor
- Must transfer property (not services) solely for stock
- Transferors must control 80% immediately after exchange
- Boot triggers gain; liabilities assumed may also trigger gain (if > basis)
- IRC §351, §358, §362
Corporate Taxable Income
- Deductions include ordinary and necessary business expenses
- Limitations on executive compensation (IRC §162(m))
- Charitable contributions limited to 10% of taxable income before certain deductions
- IRC §170, §243 (DRD)
Dividends and E&P
- Distributions taxed as dividends to extent of E&P
- Excess = return of capital (reduces basis), then capital gain
- Constructive dividends: disguised compensation or personal use
- IRC §301, §316
Stock Redemptions
- Use §302(b) tests: Not essentially equivalent, substantially disproportionate, complete termination, partial
liquidation
- Qualifying redemptions = capital gain; nonqualifying = dividend
- IRC §302, §318
Corporate Liquidations
- Complete liquidation: Gain/loss recognized by shareholders (§331) and corporations (§336)
- Subsidiary liquidations can be tax-free under §332 and §337
- IRC §331, §336, §337, §332
This study source was downloaded by 1827175 from cliffsnotes.com on 01-13-2026 18:38:32 GMT -06:00
https://www.cliffsnotes.com//study-notes/28027033
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
4:03:13 AM1
4:03:13
of 3Page
AM1
4:03:13
of1WGU
3Page
AM1 of
C239
1WGU
3Page
Final
C239
1WGU
Exam
Final
C239
KeyExam
Study
Final
KeyExam
Guide.pdf2026/10/23Page
Study
KeyGuide.pdf2026/10/23Page
Study Guide.pdf2026/10/23Page
1 of 3 1 of 3 1 of 3
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
4:03:13 AM1
4:03:13
of 3Page
AM1
4:03:13
of1WGU
3Page
AM1 of
C239
1WGU
3Page
Final
C239
1WGU
Exam
Final
C239
KeyExam
Study
Final
KeyExam
Guide.pdf2026/10/23Page
Study
KeyGuide.pdf2026/10/23Page
Study Guide.pdf2026/10/23Page
1 of 3 1 of 3 1 of 3
WGU C239 Final Exam Key Study Guide
Section 351: Transfers to Corporation Controlled by Transferor
- Must transfer property (not services) solely for stock
- Transferors must control 80% immediately after exchange
- Boot triggers gain; liabilities assumed may also trigger gain (if > basis)
- IRC §351, §358, §362
Corporate Taxable Income
- Deductions include ordinary and necessary business expenses
- Limitations on executive compensation (IRC §162(m))
- Charitable contributions limited to 10% of taxable income before certain deductions
- IRC §170, §243 (DRD)
Dividends and E&P
- Distributions taxed as dividends to extent of E&P
- Excess = return of capital (reduces basis), then capital gain
- Constructive dividends: disguised compensation or personal use
- IRC §301, §316
Stock Redemptions
- Use §302(b) tests: Not essentially equivalent, substantially disproportionate, complete termination, partial
liquidation
- Qualifying redemptions = capital gain; nonqualifying = dividend
- IRC §302, §318
Corporate Liquidations
- Complete liquidation: Gain/loss recognized by shareholders (§331) and corporations (§336)
- Subsidiary liquidations can be tax-free under §332 and §337
- IRC §331, §336, §337, §332
This study source was downloaded by 1827175 from cliffsnotes.com on 01-13-2026 18:38:32 GMT -06:00
https://www.cliffsnotes.com//study-notes/28027033
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
*@*^%^#!*&^*&^!()(@*&$*@10/23/2026,
4:03:13 AM1
4:03:13
of 3Page
AM1
4:03:13
of1WGU
3Page
AM1 of
C239
1WGU
3Page
Final
C239
1WGU
Exam
Final
C239
KeyExam
Study
Final
KeyExam
Guide.pdf2026/10/23Page
Study
KeyGuide.pdf2026/10/23Page
Study Guide.pdf2026/10/23Page
1 of 3 1 of 3 1 of 3