
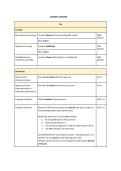
BUSINESS TIMELINES
Tax
Carrying
Non-Capital Loss Carrying Forward: 20 years (for losses arising 2005 + after) 188R
(Apndx.)
Back: 3 years
Capital Loss Carrying Forward: Indefinitely 186L
(Apndx.)
Back: 3 years
Allowable Business Forward: 10 years (after which it is a capital loss) 182R
Investment Loss (ABIL) (Apndx.)
Tax Returns
Not-For-Profit - File within 6 months after fiscal year-end 147L 7.
Information Return
Registered Charity - File within 6 months of the end of its tax year.” 147L 7.
Information Return +
Public Information Return
Corporate Tax Return Within 6 months of their year-end 194L 2.1.1
Individual Tax Return Required to file income tax return by: April 30 each year in respect of 194L 2.1.2
the preceding taxation year (calendar year).
EXCEPTION: NO return if no tax payable UNLESS:
a. No tax payable due to share purchase
b. Disposed of property in yr
c. Ind received pre-payment of child tax credit benefit in the yr
d. The MNR required a tax return filed
SELF EMPLOYED IND ( ind w business income – (includes spouse or CL
partner): has until June 15 of the following year to file.
However, interest will incur on tax owning that is NOT paid by April 30
of the year
, Trust Tax Return Filed within 90 days after fiscal year-end 194LR
inter vivos – yea-end = Dec 31, 2.1.3
Testamentary trust – the taxation year = cannot exceed 12 months
Express trust + bare trust EXCEPTIONS TRUSTS THAT NO TAX RETURN REQUIRED TO BE FILED:
also file tax returns A. Short term trust: existed less than 3 years
B. De minimus trust – holding less than 50,000 OR less in money
C. A list of trust already subject to own reporting requirements
Estate Tax Return Filed within 90 days after fiscal year-end 194L 2.1.3
Year of Death Tax Return Died after October and before May: must file not later than 6 months 194R 2.1.3
after date of death


