
YEAR END ADJUSTMENTS:
CAPITALIZED VS NON – CAPITALIZD INTEREST ON LOANS:
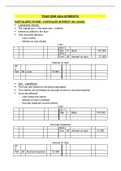
Capitalized interest
The capital sum = the total loan + interest
Interest is added to the loan
Two accounts affected
- Loan (credit)
- Interest on loan (debit)
Loan
20.1
Mar 01 Bank 100 000
20.2
Feb 28 Interest on loan 12 000
Interest on loan
20.
2
Feb 28 Loan 12 000
Non – capitalized
The loan and interest id recorded separately
The interest will be treated as accrued income or accrued expense
Accounts affected
- Loan (stays the same)
- Interest on loan (credited)
- Accrued expense/ income (debit)
Loan
20.1
Mar 1 Bank 100 000
Accrued expenses
20.2
Feb 28 Interest on loan 12 000
Interest on loan
20.
2
Feb 28 Accrued expense 12 000
, ACCRUED EXPENSES:
Liability ( credit )
Expenses still owing at year end
You paid less than what you were supposed to
Two accounts affected
- Expense (debited)
- Accrued expenses (credited)
E.g. rent expense, water and electricity, insurance, interest, telephone,
advertising, ext.
PREPAID EXPENSES:
Asset ( debited )
Expenses that already been paid for in the current financial year but only apply
for the following financial year.
You paid more than what you were supposed to.
Two accounts affected
- Expense (credited)
- Prepaid expense (debited)
Same expenses as previously mentioned.
ACCRUED INCOME:
Asset ( debited )
Income that is outstanding for the current financial year.
The business received less than what it was supposed to.
The money is still owing to the business that is why it is an asset.
Two accounts affected
- Income (credited)
- Accrued income (debited)
Rent income, interest on fixed deposits ext.
INCOME RECEIVED IN ADVANCE:
Liability ( credited )
The business received income that is only applicable for the following financial
year
The business still owes the service or good to the customer therefor making it a
liability.
Two accounts affected

