

e)
Residual
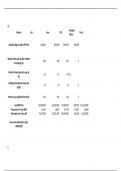
Product Gel Juice PDL Total
Fibres
Quantity (kg) at Split-off Point 100,000 300,000 600,000 200,000
Market Value per kg after Further
400 350 150 5
Processing (R)
Further Processing Costs per kg
-30 -55 -20 n.a.
(R)
Selling & Distribution Costs per
-10 -10 -10 -2
kg (R)
NRV per kg at Split-off Point (R) 360 285 120 3
Total NRV (R) 36,000,000 85,500,000 72,000,000 600,000 194,100,000
Proportion of Total NRV 0.1855 0.4405 0.3709 0.0031 1.0000
Allocated Joint Costs (R) 9,497,600 22,555,200 18,992,800 154,400 51,200,000
Joint costs allocated to juice
=R2255200
f)
, Sell after Further
Scenario Sell at Split-off Point
Processing
Selling Price per kg (R) 110 150
Further Processing Costs per kg
n.a. -20
(R)
Selling & Distribution Costs per
-4 -10
kg (R)
NRV per kg (R) 106 120
Based on the NRV calculations, it would be more beneficial for the Aloe Division to further process the PDL
before selling, as it results in a higher NRV per kg (R120) compared to selling it immediately at the split-off
point (R106).
g)
the Health Supplement Division should calculate the minimum transfer price as follows:
Minimum Transfer Price=Variable Costs+Opportunity Cost (Contribution Margin from External Sales)
Variable costs:The minimum transfer price should cover all variable costs associated with the production of
Enriched Aloe Powder
Opportunity costs :Since external demand for Enriched Aloe Powder exceeds production capacity, the division
faces an opportunity cost for not selling externally
Fixed costs and capacity utilisation:While fixed costs are generally not considered in setting transfer prices
(since they do not change with production levels), the division should ensure that internal transfers do not
lead to inefficiencies or underutilization of capacity
Residual
Product Gel Juice PDL Total
Fibres
Quantity (kg) at Split-off Point 100,000 300,000 600,000 200,000
Market Value per kg after Further
400 350 150 5
Processing (R)
Further Processing Costs per kg
-30 -55 -20 n.a.
(R)
Selling & Distribution Costs per
-10 -10 -10 -2
kg (R)
NRV per kg at Split-off Point (R) 360 285 120 3
Total NRV (R) 36,000,000 85,500,000 72,000,000 600,000 194,100,000
Proportion of Total NRV 0.1855 0.4405 0.3709 0.0031 1.0000
Allocated Joint Costs (R) 9,497,600 22,555,200 18,992,800 154,400 51,200,000
Joint costs allocated to juice
=R2255200
f)
, Sell after Further
Scenario Sell at Split-off Point
Processing
Selling Price per kg (R) 110 150
Further Processing Costs per kg
n.a. -20
(R)
Selling & Distribution Costs per
-4 -10
kg (R)
NRV per kg (R) 106 120
Based on the NRV calculations, it would be more beneficial for the Aloe Division to further process the PDL
before selling, as it results in a higher NRV per kg (R120) compared to selling it immediately at the split-off
point (R106).
g)
the Health Supplement Division should calculate the minimum transfer price as follows:
Minimum Transfer Price=Variable Costs+Opportunity Cost (Contribution Margin from External Sales)
Variable costs:The minimum transfer price should cover all variable costs associated with the production of
Enriched Aloe Powder
Opportunity costs :Since external demand for Enriched Aloe Powder exceeds production capacity, the division
faces an opportunity cost for not selling externally
Fixed costs and capacity utilisation:While fixed costs are generally not considered in setting transfer prices
(since they do not change with production levels), the division should ensure that internal transfers do not
lead to inefficiencies or underutilization of capacity


