

TAX3701 ASSIGNMENT 2 2026
DUE 4 SEPTEMBER 2027
QUESTION 1
KG Manufacturing (Pty) Ltd
Calculation of normal income tax liability for the year of assessment ended 28
February 2026
SECTION 1: GROSS INCOME
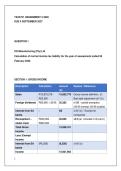
Description Calculation Amount Reason / Reference
(R)
Sales R15,875,278 - 15,852,778 Gross income definition s1;
R22,500 Bad debt adjustment (s11(i))
Foreign dividends R63,690 × 25/45 35,383 s10B – partial exemption
(20/45 exempt; 25/45 taxable)
Interest from SA – Nil s10(1)(i) - Exempt for
banks companies
Recoupment – R540,000 - 40,000 s8(4)(a) included in GI par(n)
stolen truck R500,000
Total Gross 15,928,161
Income
Less: Exempt
Income
Interest from SA (R6,258) (6,258) s10(1)(i)
banks
Income 15,921,903
1
, References: Chapter 3.2 (Gross income definition), 3.4.2 (Interest exemption), 3.6.2
(Foreign dividends), 5.13.4 (Recoupments)
SECTION 2: COST OF SALES (s22)
Description Reason Amount (R)
Opening stock Lower of cost (R2,571,279) or MV (R2,552,351) (2,552,351)
Purchases s22 – Deductible (7,500,126)
Closing stock Lower of cost (R2,625,871) or MV (R2,631,250) 2,625,871
Net Cost of Sales (7,426,606)
Reference: Chapter 4.3 (Trading stock – lower of cost or market value)
SECTION 3: DEDUCTIONS AND ADJUSTMENTS
2
DUE 4 SEPTEMBER 2027
QUESTION 1
KG Manufacturing (Pty) Ltd
Calculation of normal income tax liability for the year of assessment ended 28
February 2026
SECTION 1: GROSS INCOME
Description Calculation Amount Reason / Reference
(R)
Sales R15,875,278 - 15,852,778 Gross income definition s1;
R22,500 Bad debt adjustment (s11(i))
Foreign dividends R63,690 × 25/45 35,383 s10B – partial exemption
(20/45 exempt; 25/45 taxable)
Interest from SA – Nil s10(1)(i) - Exempt for
banks companies
Recoupment – R540,000 - 40,000 s8(4)(a) included in GI par(n)
stolen truck R500,000
Total Gross 15,928,161
Income
Less: Exempt
Income
Interest from SA (R6,258) (6,258) s10(1)(i)
banks
Income 15,921,903
1
, References: Chapter 3.2 (Gross income definition), 3.4.2 (Interest exemption), 3.6.2
(Foreign dividends), 5.13.4 (Recoupments)
SECTION 2: COST OF SALES (s22)
Description Reason Amount (R)
Opening stock Lower of cost (R2,571,279) or MV (R2,552,351) (2,552,351)
Purchases s22 – Deductible (7,500,126)
Closing stock Lower of cost (R2,625,871) or MV (R2,631,250) 2,625,871
Net Cost of Sales (7,426,606)
Reference: Chapter 4.3 (Trading stock – lower of cost or market value)
SECTION 3: DEDUCTIONS AND ADJUSTMENTS
2



