

TAX2601 ASSIGNMENT 1 2026
DUE 4 SEPTEMBER 2026
QUESTION 1 Portia Financial Advisory (Pty) Ltd (“PFA”), a South African resident
company that provides financial advice and investment services to clients. PFA
has a financial year ending on 28 February.
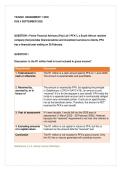
QUESTION 1
Discussion: Is the R1 million held in trust included in gross income?
Requirement Discussion
1. Total amount in The R1 million is a cash amount paid to PFA on 1 June 2025.
cash or otherwise The amount is ascertainable and quantifiable.
2. Received by, The amount is received by PFA, but applying the principle
accrued to, or in in Geldenhuys v CIR (14 SATC 419), an amount is only
favour of “received” if it is for the taxpayer’s own benefit. PFA holds the
funds in a separate bank account and is contractually obliged
to return any uninvested portion. It acts as an agent/trustee,
not as the beneficial owner. Therefore, the amount is NOT
received for PFA’s own benefit.
3. Year of assessment If it were taxable, it would fall into the 2026 year of
assessment (1 March 2025 – 28 February 2026). However,
because the “received” requirement is not met, this criterion is
not reached.
4. Excluding amounts The R1 million is not capital in nature to PFA, but this is
of a capital nature irrelevant as the amount fails the “received” test.
Conclusion The R1 million is not included in PFA’s gross income. Only
the 5% fee on returns generated will constitute income.
(Reference: LU 4 Gross Income Definition)
, QUESTION 2
Eddy’s Electronics (Pty) Ltd – YOA: 1 June 2025 – 31 May 2026
(a) First Provisional Tax Payment
Reason
Year of
assessment
2023 R7,950,000; assessed 20 Oct 2023. Issued >14 days before 30
Nov 2025. Period from 31 May 2023 to 30 Nov 2025 >18 months,
so adjust by 8% for 3 years (2024, 2025, 2026).
2024 R8,123,500; assessed 27 Nov 2025. Issued within 14 days of 30
Nov 2025 – cannot be used.
2025 Not assessed before due date – cannot be used.
2026 Estimated amount cannot be used for first payment.
Due date: 30 November 2025 (last day of the 6th month of the YOA).
Basic amount = R7,950,000 × (1 + 0.08 × 3) = R9,858,000.
Tax @ 27% = R2,661,660.
First payment (50%) = R1,330,830.
(b) Second Provisional Tax Payment
Due date: 31 May 2026 (last day of the YOA).
DUE 4 SEPTEMBER 2026
QUESTION 1 Portia Financial Advisory (Pty) Ltd (“PFA”), a South African resident
company that provides financial advice and investment services to clients. PFA
has a financial year ending on 28 February.
QUESTION 1
Discussion: Is the R1 million held in trust included in gross income?
Requirement Discussion
1. Total amount in The R1 million is a cash amount paid to PFA on 1 June 2025.
cash or otherwise The amount is ascertainable and quantifiable.
2. Received by, The amount is received by PFA, but applying the principle
accrued to, or in in Geldenhuys v CIR (14 SATC 419), an amount is only
favour of “received” if it is for the taxpayer’s own benefit. PFA holds the
funds in a separate bank account and is contractually obliged
to return any uninvested portion. It acts as an agent/trustee,
not as the beneficial owner. Therefore, the amount is NOT
received for PFA’s own benefit.
3. Year of assessment If it were taxable, it would fall into the 2026 year of
assessment (1 March 2025 – 28 February 2026). However,
because the “received” requirement is not met, this criterion is
not reached.
4. Excluding amounts The R1 million is not capital in nature to PFA, but this is
of a capital nature irrelevant as the amount fails the “received” test.
Conclusion The R1 million is not included in PFA’s gross income. Only
the 5% fee on returns generated will constitute income.
(Reference: LU 4 Gross Income Definition)
, QUESTION 2
Eddy’s Electronics (Pty) Ltd – YOA: 1 June 2025 – 31 May 2026
(a) First Provisional Tax Payment
Reason
Year of
assessment
2023 R7,950,000; assessed 20 Oct 2023. Issued >14 days before 30
Nov 2025. Period from 31 May 2023 to 30 Nov 2025 >18 months,
so adjust by 8% for 3 years (2024, 2025, 2026).
2024 R8,123,500; assessed 27 Nov 2025. Issued within 14 days of 30
Nov 2025 – cannot be used.
2025 Not assessed before due date – cannot be used.
2026 Estimated amount cannot be used for first payment.
Due date: 30 November 2025 (last day of the 6th month of the YOA).
Basic amount = R7,950,000 × (1 + 0.08 × 3) = R9,858,000.
Tax @ 27% = R2,661,660.
First payment (50%) = R1,330,830.
(b) Second Provisional Tax Payment
Due date: 31 May 2026 (last day of the YOA).


