

MAC3701 ASSIGNMENT 2 2026
DUE 14 SEPTEMBER 2026
PART A As part of the budgeting process for the year ending 31 December 2027,
EVD’s management is assessing the impact of increased competition from international
electric vehicle manufacturers.
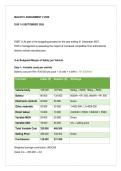
A-a) Budgeted Margin of Safety per Vehicle
Step 1: Variable costs per vehicle
Battery cost per kWh: R30 000 per pack ÷ (4 cells × 5 kWh) = R1 500/kWh
Cost Item Urban (R) Explorer (R) Workings
Vehicle body 125 000 187 500 500kg × R250; 750kg × R250
Battery 90 000 135 000 60kWh × R1 500; 90kWh × R1 500
Electronic controls 40 000 50 000 Given
Other materials 20 000 30 000 1×R20 000; 1,5×R20 000
Direct labour 12 000 18 000 2 400/60 × R300; 3 600/60 × R300
Variable MOH 20 000 20 000 Given
Variable S&D 18 000 28 000 4% × selling price
Total Variable Cost 325 000 468 500
Selling Price 450 000 700 000 Given
Contribution 125 000 231 500
Weighted average contribution (WACM)
Sales mix = 300:200 = 3:2
, WACM = (125 000 × 3/5) + (231 500 × 2/5) = 75 000 + 92 600 = R167 600
(Drury, 2020, Ch 8; Study Unit 14 – multi-product CVP)
Fixed costs
Fixed MOH = (300 + 200) × R125 000 = R62 500 000
Total S&D = R28 110 000
Variable S&D = 4% × [(300×450 000) + (200×700 000)] = 4% × R275 000 000 =
R11 000 000
Fixed S&D = R28 110 000 – R11 000 000 = R17 110 000
Total Fixed Costs = R79 610 000
Break-even & Margin of Safety
B/E units = R79 610 000 ÷ R167 600 = 475 units
Budgeted sales = 500 units
MOS (units) = 500 – 475 = 25 units
MOS (%) = 25/500 = 5%
(Drury, 2020, Ch 8; Study Unit 4 – margin of safety)
MOS per vehicle:
Urban: 25 × 3/5 = 15 units
Explorer: 25 × 2/5 = 10 units
DUE 14 SEPTEMBER 2026
PART A As part of the budgeting process for the year ending 31 December 2027,
EVD’s management is assessing the impact of increased competition from international
electric vehicle manufacturers.
A-a) Budgeted Margin of Safety per Vehicle
Step 1: Variable costs per vehicle
Battery cost per kWh: R30 000 per pack ÷ (4 cells × 5 kWh) = R1 500/kWh
Cost Item Urban (R) Explorer (R) Workings
Vehicle body 125 000 187 500 500kg × R250; 750kg × R250
Battery 90 000 135 000 60kWh × R1 500; 90kWh × R1 500
Electronic controls 40 000 50 000 Given
Other materials 20 000 30 000 1×R20 000; 1,5×R20 000
Direct labour 12 000 18 000 2 400/60 × R300; 3 600/60 × R300
Variable MOH 20 000 20 000 Given
Variable S&D 18 000 28 000 4% × selling price
Total Variable Cost 325 000 468 500
Selling Price 450 000 700 000 Given
Contribution 125 000 231 500
Weighted average contribution (WACM)
Sales mix = 300:200 = 3:2
, WACM = (125 000 × 3/5) + (231 500 × 2/5) = 75 000 + 92 600 = R167 600
(Drury, 2020, Ch 8; Study Unit 14 – multi-product CVP)
Fixed costs
Fixed MOH = (300 + 200) × R125 000 = R62 500 000
Total S&D = R28 110 000
Variable S&D = 4% × [(300×450 000) + (200×700 000)] = 4% × R275 000 000 =
R11 000 000
Fixed S&D = R28 110 000 – R11 000 000 = R17 110 000
Total Fixed Costs = R79 610 000
Break-even & Margin of Safety
B/E units = R79 610 000 ÷ R167 600 = 475 units
Budgeted sales = 500 units
MOS (units) = 500 – 475 = 25 units
MOS (%) = 25/500 = 5%
(Drury, 2020, Ch 8; Study Unit 4 – margin of safety)
MOS per vehicle:
Urban: 25 × 3/5 = 15 units
Explorer: 25 × 2/5 = 10 units


