
Practice Final Exam ECON B251
1. The current price in a perfectly competitive market for gasoline is $1, and each firm is
producing 100 units (gallons), and at this output the average total cost (ATC) of those
100 units is $3. Given this information each firm’s current profits are which of the
following?
a. $1,000
b. $800
c. $-200
d. $200
2. The current price in a perfectly competitive market for gasoline is $1, and each firm is
producing 100 units (gallons), and at this output the average total cost (ATC) of those
100 units is $3. Given this information in the long run firms will ________, and profits
will be ___________?
a. Exit ; Positive
b. Exit ; Zero
c. Enter ; Positive
d. Enter ; Negative
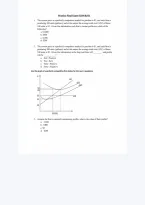
Use the graph of a perfectly competitive firm below for the next 4 questions:
P
MC
ATC
AVC
50
40
30 MR
25
10
2030Q
3. Assume the firm is currently maximizing profits, what is the value of their profits?
a. -$100
b. -$400
c. $0
d. $200
, 4. Assume that firms enter the market above. The new equilibrium price __________ , and
profits of the existing firms will _____________.
a. Increases ; increase
b. Increases ; decrease
c. Decreases ; decrease
d. Decreases ; increase
5. Assume that the price of the good for the firm depicted above falls in the short run to $20.
In the short run the firm should___________, and their profits will be ___________.
a. Shutdown ; -$300
b. Continue to Operate ; -$400
c. Continue to Operate -$500
d. Shutdown ; $0
6. Which of the following is NOT true of a perfectly competitive firm in the long run?
a. Price = Average Total Costs
b. Average Total Cost = Marginal Cost
c. Fixed Costs are zero
d. P = min. Average Total Costs
e. Average Variable Cost < Average Total Cost

